Case Study
Residential Home Building

No Will, No Savings, No Plan: How One Home Builder Got Out of Successful Chaos

$4.3M to $11M in Revenue

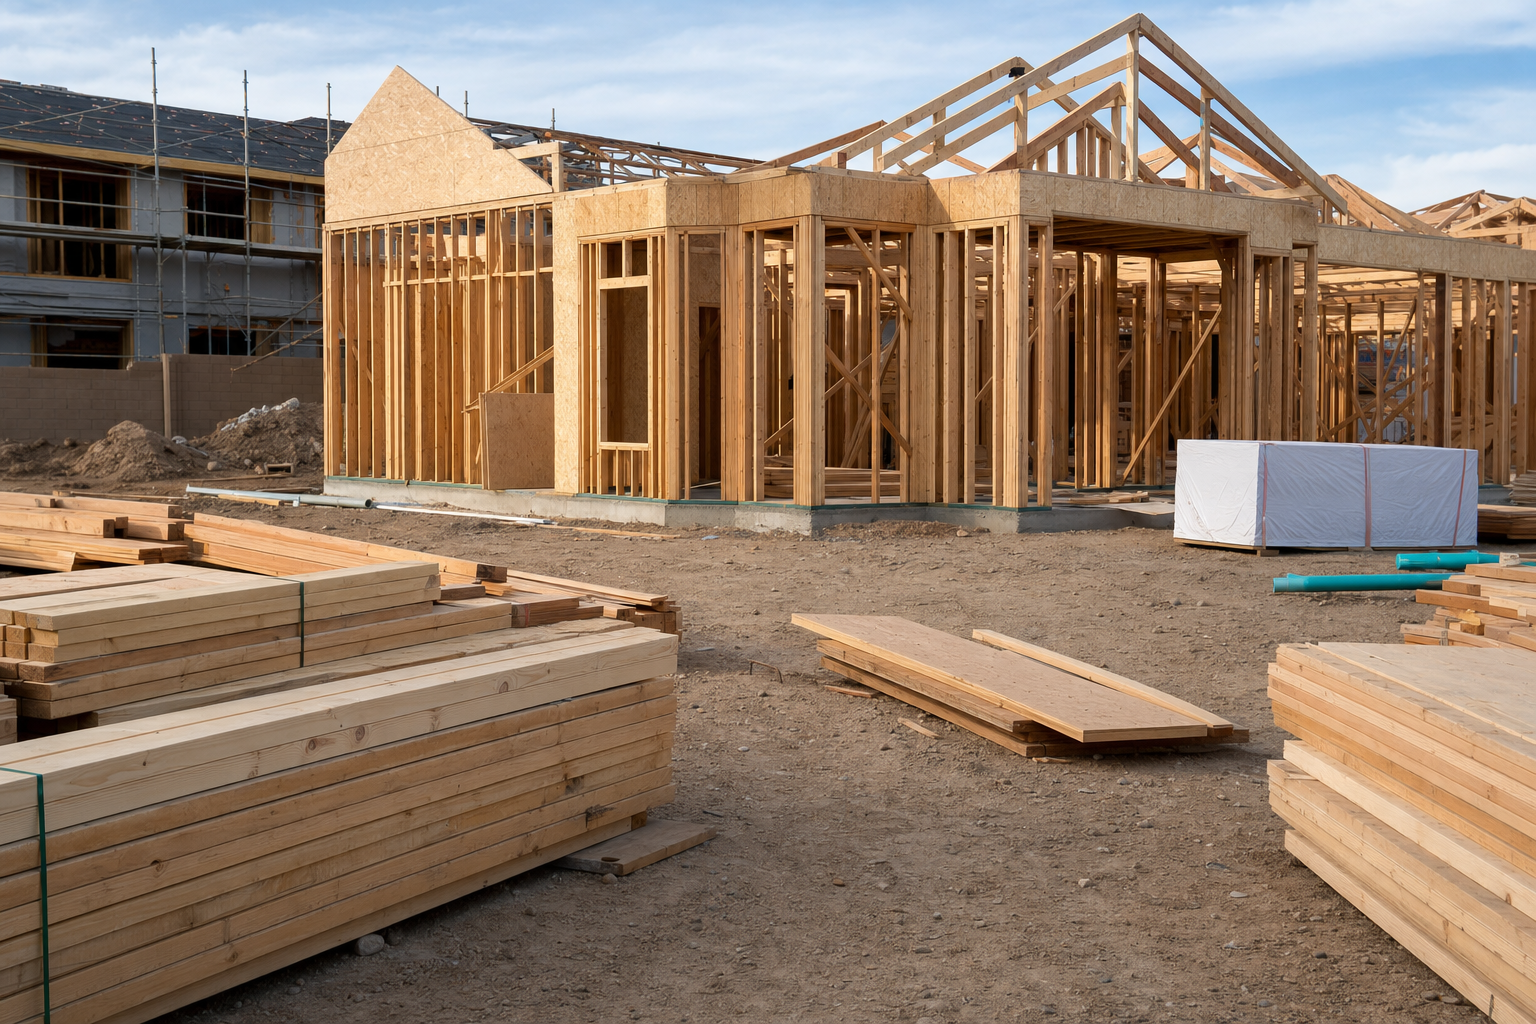
Residential home construction job site with wood framing and building materials, representative of the home building industry in this story

Grant ran a $4.3 million home building company with no will, no trust, and no life insurance protecting his family. He had no personal savings to speak of, no retirement plan beyond the business itself, and no plan for what would happen to the company without him. Three years later, revenue had grown to $11 million, he had built $400,000 in personal savings, and his family was finally protected.

The Situation

On paper, Grant was winning. His home building company was generating $4.3 million a year in revenue, and the work kept coming. In practice, he had no will, no trust, and no life insurance in place. If something happened to him, his family would have been left exposed with no plan and no protection.

There was no personal savings to speak of and no retirement plan beyond the business itself. There was no HR infrastructure to support his growing crew, and no leadership transition plan if he needed to step back. Every dollar the business produced went right back into the business. He had a growing company and no home builder financial plan connecting it to his personal life. That gap, real success on the outside and real fragility underneath, is what we call Successful Chaos™.

What We Did

  • —Built a full strategic wealth plan: a will, a trust, and life insurance to protect Grant's family regardless of what happened to the business.
  • —Improved the retirement plan: added profit sharing to the company retirement plan so Grant and his team could build wealth outside the business itself.
  • —Implemented a PEO: brought in a professional employer organization to give the whole team better health insurance.
  • —Brought in Bamboo HR: built real hiring and retention infrastructure where none had existed before.
  • —Extended planning to the executive team: personal wealth planning wasn't reserved for Grant alone. His leadership team got the same attention, which strengthens the business he'll eventually hand off.

Each piece did the same job. It ran the complexity around Grant, not through him.

The Result

$4.3M → $11M

Revenue Growth

$400K in 2 Years

Personal Savings

~$160K

Tax Savings Identified

Three years in, Grant's company grew from $4.3 million to $11 million in revenue. That growth happened alongside the personal protection work, not instead of it.

Grant built $400,000 in personal savings in two years, something he had never managed in the business's earlier, more chaotic seasons. We identified roughly $160,000 in tax savings along the way. His family is now fully protected with a will, trust, and life insurance in place, and his estate is no longer an open question if something happens to him.

Just as important, Grant now has a real path to an eventual exit. That starts with an honest business valuation and ongoing exit planning, not a fire drill forced by a health scare, a burnout moment, or a buyer's forced timeline. He's exit-ready. He was never exit-pressured.

Is This Where You Are?

If you're running a home building business, or any trades business, generating real revenue while you personally have no will, no savings, and no plan beyond the business itself, you're not alone. Most owners we meet are winning on paper while carrying all the risk in practice.

You don't need to have it figured out before we talk. Start with a free GAP Assessment and find out where you actually stand, on paper and in practice. Schedule your free GAP Assessment.

Frequently Asked Questions

What does "Successful Chaos" mean?
Successful Chaos™ describes a business that looks strong from the outside, healthy revenue, steady work, a growing team, while the owner personally carries all the risk. No protection, no savings, no plan beyond the business itself. Grant's company before this work is a clear example: $4.3 million in revenue and almost nothing standing between his family and disaster.
How did revenue grow from $4.3M to $11M while also fixing Grant's personal financial gaps?
The two tracks ran together, not separately. As Chief of Staff coordinating Grant's CPA, attorney, and insurance advisors, the team built the strategic wealth plan (will, trust, life insurance) and improved his retirement plan alongside operational fixes like the PEO for health insurance and Bamboo HR for hiring and retention. A business can't scale cleanly while its owner is personally unprotected. Fixing both at once is what let the company grow from $4.3M to $11M over three years.
Does this kind of transformation apply outside of home building?
The pattern applies to any owner-operated business where the company looks strong on paper but the owner has no personal protection in practice. Grant's industry was residential home building, but the gaps found there — no will, no trust, no life insurance, no savings outside the business, no leadership transition plan — are common across founder-led companies of similar size. The fix is the same regardless of industry: build the plan, then extend it past the owner.
What did the Chief of Staff role actually mean in Grant's engagement?
It meant one accountable operator coordinating every piece of Grant's plan instead of Grant juggling separate advisors on his own. The will, trust, and life insurance work, the retirement plan improvements, the PEO transition, and the Bamboo HR rollout were quarterbacked as one connected plan rather than isolated projects, and personal wealth planning was extended to Grant's executive team, not just Grant, so the business isn't solely dependent on him. Three years in, Grant has built $400,000 in personal savings, identified roughly $160,000 in tax savings, and has a real path to an eventual exit. He hasn't executed that exit, and doesn't need to — he's exit-ready, never exit-pressured.